Access both platforms from your single Saxo account.

Asia Market Quick Take – 12 November, 2026
Key points:
- Macro: NYT reports another relationship scandal regarding Jensen Huang
- Equities: Nvidia falls after-hours due to 2nd relationship scandal
- FX: BBG USD Index at highest level since May 2025
- Commodities: Gold back below $4,000 on rate hike expectations
- Fixed income: US curve twist-flattens; front-end jumps, hedging demand surges on tightening
------------------------------------------------------------------
Disclaimer: Past performance does not indicate future performance.
Macro:
- The Bank of Canada is preparing to launch a formal search for Macklem’s successor, with Macklem expected to announce his plans soon.
- The NYT reported allegations of a relationship between CEO Jensen Huang and an executive, while the WSJ said the board was preparing to remove him. Turmoil at Nvidia could have broader global market repercussions given its central role in the AI boom.
- Japan’s producer prices rose 7.1% yoy in October, above expectations and September’s 6.8%, signaling renewed upstream inflation amid a weaker yen and higher input costs. Prices were broadly higher across key sectors, and the monthly gain of 0.7% was the fastest in five months.
- US–Iran talks are deadlocked, with Tehran refusing to give up enriched nuclear material and insisting on sanctions relief and an end to the naval blockade before reopening the Strait of Hormuz. Ukrainian drones have hit refineries handling about 30% of Russia’s oil-processing capacity, but US oil prices remain nearly 20% below their October peak as Middle East supply recovers.
- Waller’s remarks and the hotter CPI report triggered repricing, while Paulson (2026 voter) warned the Fed could move more aggressively if inflation worsens but maintained that gradual hikes remain appropriate and data-dependent.
Equities:
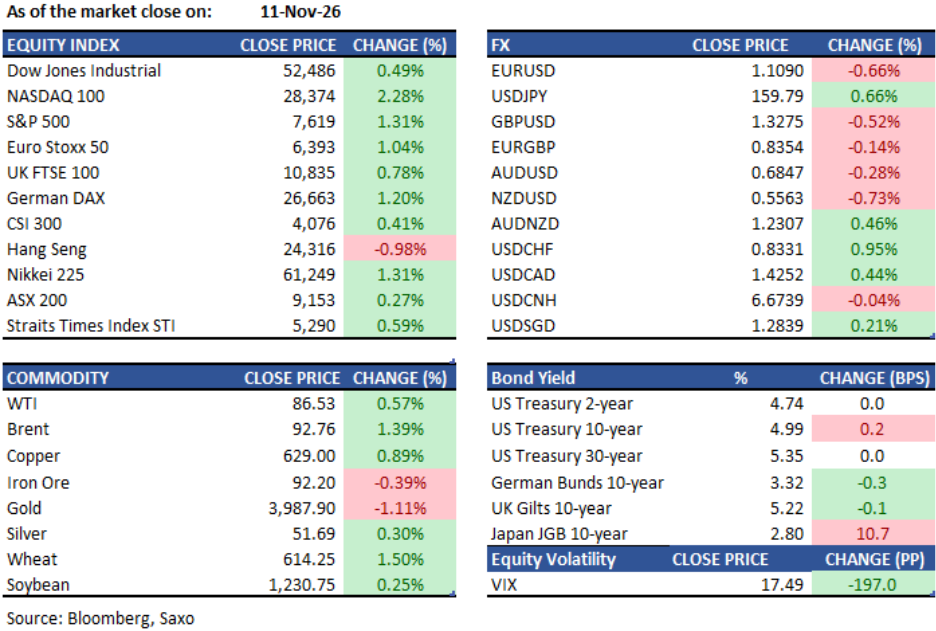
- US — The S&P 500 gained 1.3% to 7,619 and the Nasdaq 100 surged 2.3% on Wednesday, before the AI trade was rocked after hours by a cascade of Nvidia CEO Jensen Huang revelations. The New York Times reported Huang had a second affair — with Kimberly Powell, Nvidia's VP of Healthcare, who reports directly to him — on top of his previously disclosed relationship with a woman US officials reportedly believe to be a Chinese spy. The Wall Street Journal subsequently reported that Nvidia's board is preparing to oust Huang, and Bloomberg separately reported the board has been working with an outside firm to identify potential CEO replacements, including the possibility of naming a temporary chief. Nvidia shares fell as much as 10% after hours. Bernstein cut Nvidia to Market Perform and slashed its PT to $200 from $400—the day’s second downgrade—after a report alleging the board may oust CEO Jensen Huang; shares fell 8% to $160 after-hours. CoreWeave dropped more than 7% in sympathy, with IREN and Nebius each falling more than 4%. Earlier CoreWeave shares jumped 25% to $60.77—its biggest one-day gain since June 2025—after easing debt concerns, raising its full-year revenue outlook to $13.0–$13.3B above the $12.9B consensus, and signaling an imminent investment-grade loan amid resilient sales growth. Nasdaq 100 futures are down 0.9% and S&P 500 futures off 0.4% as of early Thursday morning HKT. Separately, Congress is reportedly preparing to subpoena Huang after he did not respond by Wednesday's deadline to a request to appear for a closed-door briefing. Nvidia's next earnings are scheduled for November 17. Anthropic’s IPO is multiple-times oversubscribed on anchor interest as it seeks up to $90.4B—potentially the biggest listing ever—with details subject to change and no company comment.
- EU — European equity markets were supported by the broader AI-driven recovery in global risk sentiment on Wednesday. Stoxx 600 earnings season continues to show resilience, with tech hardware and semiconductor revenue beats outpacing misses 10-to-0, and financial services beats outpacing misses 7-to-3. Taylor Wimpey warned that its full-year operating profit would land at the bottom end of consensus, citing higher mortgage rates and weaker buyer demand in the UK. UniCredit reported record quarterly net income of €3.26 billion in Q3, beating all estimates, as CEO Andrea Orcel advances on Commerzbank.
- Asia — Asian markets are opening cautiously on Thursday morning. The Kospi opened up 0.2% at 5,385.94, showing resilience despite the Nvidia after-hours selloff. The Nikkei is also modestly higher in early trade, with Japanese auto stocks continuing to benefit from lower oil prices and easing Middle East tensions following the US midterm outcome. The STI gained 0.6% on Wednesday to 5,289.66, led by Venture Corp which rose 5.2% after strong Q3 results. Taiwan is the key market to watch given its heavy Nvidia supply-chain exposure, with TSMC having risen 4.8% on Wednesday after strong October revenue data. Two new Hong Kong IPOs — Hosin Electronics and Amicro Technology — begin trading today, having raised a combined HK$1.78 billion. MSCI announced its quarterly index review, with Sands China deleted from Hong Kong and Nissan Motor among deletions in Japan, effective November 30.
Earnings this week:
- Thursday: SMIC; Bridgestone; Inpex; Cisco; Siemens; Allianz; Merck; Applied Materials
- Friday: MUFG; Sumitomo Mitsui Financial; Mizuho Financial; Japan Post Bank; Singtel; Generali
FX:
- USD strengthened with the Bloomberg Dollar Spot Index climbed to its highest level since May 2025 on Wednesday, gaining 0.4% as the hot CPI print and hawkish Fed commentary reinforced rate hike expectations across the curve.
- USDJPY rose to 159.65–159.80, nearing the psychologically significant 160 level. The pair has broken above the September 24 high of 159.04, with technicals pointing toward a test of the September 2 high at 160.39. The yen remains under pressure as it stays hostage to US rate differentials.
- EURUSD touched its lowest level against the dollar since earlier in 2026, with analysts flagging that the snap-back in rate differentials following the CPI shock gives the euro room to fall further to fresh 2026 lows.
- AUDUSD fell to a seven-month low of 0.6844, its weakest since March 31, with consumer inflation expectations data due Thursday adding to uncertainty around the RBA's policy path.
- KRW was the best-performing EM currency, strengthening 0.44% against the dollar, supported gains in Korean chipmakers including SK Hynix and Samsung on the AI trade rebound.
Commodities:
- Gold fell below $4,000 an ounce during US trading hours on Wednesday — extending a 2.6% decline from Tuesday — as the stronger dollar and rising rate-hike expectations weighed on bullion. Gold is struggling to reclaim its safe-haven role, trading more as an expression of the rates narrative than a traditional haven.
- Oil extended its decline on hopes for a diplomatic resolution to the Middle East conflict following the US midterm election result, with Brent falling sharply from recent highs above $117/bbl to below $90/bbl. Lower oil is providing a tailwind for Japanese automakers and easing some inflationary pressure at the margin.
- Aluminum is in the grip of a severe supply squeeze on both the LME and Shanghai exchanges, with spot metal trading at a premium to later-dated futures (backwardation) due to declining stockpiles and constrained immediate delivery. Buyers face rising spot prices with little near-term relief in sight.
Fixed income:
- The US Treasury curve twist-flattened as cash trading resumed Thursday in Asia, with the 2-year yield rising 4bps to 4.77% and the 10-year little changed at 4.99%, while the 30-year retreated 2bps to 5.33%. The 2-year had surged as much as 20bps on Tuesday — the largest single-day move since April 2025 — following the CPI beat and hawkish Fedspeak.
- The 10-year yield is hovering just below the 5% threshold, with Treasury futures implying a breach of that level when cash markets fully reopen. JPMorgan warned that if the hawkish tone from Fed officials spreads more broadly across the committee, a more decisive bond selloff and further curve flattening could follow.
- T-bill market dislocations emerged following the CPI shock, with the very front end holding a bid while the one-year competed with the 2-year in the selloff. SOFR options volumes ran approximately 80% above the 20-day average on Tuesday, with new risk heavily skewed toward downside protection, reflecting growing demand for hedges against further Fed tightening.
For a global look at markets – go to Inspiration.
This content is marketing content and should not be considered investment advice. Trading financial instruments carries risks and historic performance is not a guarantee for future performance.
The instrument(s) mentioned in this content may be issued by a partner, from which Saxo receives promotion, payment or retrocessions. While Saxo receives compensation from these partnerships, all content is conducted with the intention of providing clients with valuable options and information.