Access both platforms from your single Saxo account.

Asia Market Quick Take – 02 November, 2026
Asia Market Quick Take – 2 November, 2026
Key points:
- Macro: BOJ holds rates at 1.25% in 8-1 vote.
- Equities: Nasdaq down 2.9%. INTC -28.6%; AMD -10.9%; RDDT -29.2%
- FX: Norwegian krone is the best-performing G10 currency YTD
- Commodities: Gold breaks below $3,900 and silver below $50
- Fixed income: US Treasuries bull-steepened; issuance at record levels
------------------------------------------------------------------
Disclaimer: Past performance does not indicate future performance.
Macro:
- The BoJ kept its short-term rate at 1.25% in 8-1 vote, its highest since 1995, and signaled room for further hikes as inflation nears 2%. One member dissented, urging faster tightening. The bank kept its FY2026 inflation forecast at 2.5%, raised growth to 0.7%, and for FY2027 lifted inflation to 2.6% while cutting growth to 0.7%.
- China’s NBS Manufacturing PMI fell to 49.3 in October 2026 from 50.1, missing expectations and returning to contraction as demand weakened and business confidence hit a seven‑month low.
- Qatari and Iranian officials met for a third day to seek a deal to halt the US-Israel war on Iran before US midterms. Iran warned new attacks would trigger retaliation, while Trump pledged no fresh strikes before the vote but left post-election action open. OPEC+ kept oil output targets unchanged through December.
- Australia’s Manufacturing PMI was revised to 49.6 in October 2026, matching September’s 21‑month low and signaling a second month of contraction, with sharply lower new orders, weaker output, worsening delivery times, and rising input and output prices.
- Germany’s annual inflation fell to 2.8% in October 2026 from 3.3%, below expectations, helped by a temporary fuel tax cut. Core inflation dropped to 2.1%, while the EU‑harmonized rate eased to 2.8%, still above the ECB’s 2% target.
- US civilian worker compensation rose 0.8% in Q3 2026, slightly less than Q2’s 0.9%. Wages and salaries were up 0.7%, benefits 0.9%. Year-on-year, employment costs increased 3.4%.
- The euro area unemployment rate was unchanged at 6.5% in September, near its record low and well below the long‑term average of 9.1%.
- Eurozone GDP grew 0.4% in Q3 2026, beating the 0.2% forecast but down from 0.6% in Q2. Ireland jumped 5.5%, Spain and the Netherlands 0.6%, Germany 0.2%, while France fell 0.1% and Italy was flat. Strong AI, defense, and infrastructure spending supports growth, but the ECB warns higher rates and energy costs could slow it.
Equities:
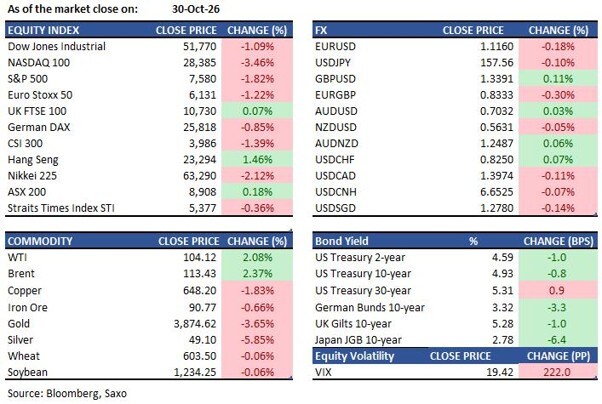
- US: US equities suffered their worst session in four months on Friday, driven by a tech rout following disappointing earnings from Amazon and Intel. S&P 500 fell 1.8%, the Dow dropped 1.1%, and the Nasdaq Composite shed 2.9% — capping the Nasdaq's worst month since March 2025. Intel cratered 28.6% for its steepest decline in over four decades. Reddit plunged 29.2% and AMD fell 10.9%. On the upside, FedEx Freight surged 14.9% and Regeneron gained 13.3%. In after-hours trade, US equity futures opened higher Sunday evening, offering some relief ahead of Monday's Asia open. Over the weekend, Meta’s credit outlook was cut to negative from stable by S&P.
- EU: European equities were mixed on Friday, with the Stoxx 600 falling 0.4%, led lower by banks and tech. The DAX declined 0.9%, with Siemens Energy dropping 6.9%. The FTSE 100 was broadly flat (+0.07%), supported by AstraZeneca, which surged 7.0% on strong earnings. The CAC 40 was essentially unchanged (-0.01%). European chip stocks were broadly lower in sympathy with the US tech selloff — ASML fell 4.7%, AT&S dropped 13.3%. For the month, the Stoxx 600 gained 1.9%, outperforming the S&P 500 by 2.9 percentage points.
- Asia: Asian equities opened sharply lower Monday, tracking Friday's Wall Street selloff. The KOSPI fell 1.6% at the open to 5,637.77, led by semiconductor names. The Nikkei and broader Asian tech benchmarks faced further pressure, with Kioxia's downbeat profit forecast adding to the negative tone for memory stocks. The Topix fell 0.7%. The MSCI AC Asia Pacific Index lost 0.4%. China's PBOC-CSRC meeting on capital market support offered a potential floor for HK-listed stocks; Goldman Sachs removed Hong Kong Exchanges from its APAC Conviction List, while Yokohama was added. Australia's ASX 200 fell 0.3% to 8,878.70, with mining and consumer staples weighing, ahead of a busy week of earnings and the RBA decision.
Earnings this week:
FX:
- USDJPY trades at 157.73, up modestly on the day. The yen had been supported by risk-off flows and hedge fund short-covering through last week, but the dollar is catching a small bid in early Monday trade. The yen remains in the mid-157 range, with the BOJ's hold and hawkish signals keeping the pair in a tight range.
- AUDUSD softens to 0.7029, down ~0.04% on the day, pressured by risk-off sentiment. The pair faces headwinds despite an expected RBA hike on Tuesday, as the move is largely priced in by swaps markets (~80% probability). The AUD had rallied ~2% since mid-October on hot Q3 inflation data.
- EURUSD holds near 1.1159, down marginally. The euro fell 0.4% last week and remains under pressure from the broader dollar bid and European energy concerns, with Germany missing its gas storage target of 70% ahead of winter.
- GBPUSD at 1.3387, little changed. Sterling rose 0.1% last week and is steady ahead of the BOE rate decision on Thursday, where a hike is widely expected.
- Norwegian krone is the best-performing G10 currency year-to-date, up 9.6% against the dollar at 9.20, benefiting from elevated oil prices. The Swedish krona is the worst performer, down 6.3% YTD at 9.83.
Commodities:
- Oil (WTI) trades at $102.31/bbl, down 1.7% on the day, despite OPEC+ reaffirming unchanged December output quotas and fresh Strait of Hormuz incidents involving two tankers reportedly catching fire after hitting naval mines. Oil is declining ahead of Tuesday's US midterm elections, with Secretary of State Rubio signalling no decision on fresh Iran strikes and a preference for diplomacy. Goldman Sachs raised its December 2026 Brent forecast to $105/bbl from $90, citing sustained geopolitical supply risk.
- Gold recovers to $3,902.96/oz, up 0.7% on the day, as dip buyers return after a 3.7% slump on Friday that pushed bullion to its lowest level in a year. October was gold's worst month since 2008. Lower oil prices are offering some relief from inflationary pressures, supporting the metal.
- Silver gains 1.5% to $49.85/oz, also recovering from Friday's selloff. Copper edges up 0.5% to 651.25 USd/lb, supported by China's capital market support signals, though both metals remain under pressure from the broader risk-off environment and AI spending concerns.
Fixed income:
- US Treasuries bull-steepened on Friday as the tech rout drove a flight-to-quality bid. The 10-year yield fell ~1bp to 4.93% on Friday, with the front-end and belly outperforming. Volumes in 10-year note futures spiked sharply, consistent with buyers. The 5s30s spread widened to 59.5bps from 55.9bps. As of Monday, the 10-year yield has edged back up ~1.5bps to 4.95%, the 2-year sits at 4.60%, and the 30-year is at 5.33%.
- US Treasury issuance at record levels. The US government borrowed a record $839 billion via bill and note auctions last week, eclipsing the prior record of $834 billion set a year ago. The Treasury General Account breached $1 trillion, draining bank reserves to $2.9 trillion. Wall Street is bracing for a significant overhaul in issuance guidance at Wednesday's quarterly refunding announcement.
- JGBs and global bonds rallied on Friday alongside Treasuries, with the BOJ holding rates steady. The 10-year JGB yield had earlier reached a 30-year high of 3.14% this month. Investors are reportedly returning to long-dated government bonds as yields near multi-decade highs become difficult to resist, particularly with equities looking expensive and volatile. PGIM warns that US Treasuries are set to underperform global sovereign bonds over the next 6–18 months given the US's unique combination of growth and inflation pressures.
For a global look at markets – go to Inspiration.
This content is marketing content and should not be considered investment advice. Trading financial instruments carries risks and historic performance is not a guarantee for future performance.The instrument(s) mentioned in this content may be issued by a partner, from which Saxo receives promotion, payment or retrocessions. While Saxo receives compensation from these partnerships, all content is conducted with the intention of providing clients with valuable options and information.