You can access all of our platforms from a single Saxo account.

The vote week outprices the month - Options Brief - 3 November 2026
Summary: The nine-day VIX jumped above the 30-day gauge on Monday, with today’s vote, the Treasury refunding and payrolls all inside its window. Is that an event premium that drains by Friday, or the edge of a higher floor?
The nine-day volatility gauge rose nearly twice as fast as the VIX on Monday and now sits above it, with the vote, the refunding and payrolls inside its window.
MARKET REGIME: NEUTRAL / CHOP | VIX 21.15 | TERM STRUCTURE: FLAT | SKEW: ELEVATED (152.78) | FRONT-MONTH VIX FUTURES: 20.650
Today in brief
The nine-day volatility gauge, which covers today’s midterm vote, Wednesday’s Treasury refunding and Friday’s payrolls, jumped 16.68% to 22.46 on Monday. That put it above the 30-day VIX at 21.15, a ratio of 1.062, only the fourth reading above one in our 101-session store. The one-day gauge went the other way, down 7.40% to 17.90. Options indicatively price 0.86% for today’s expiry and 1.85% for the 6 November expiry, against about 1.65% that time decay alone would have left from yesterday’s reading, so in our view the market added premium to this week for a second day.
In our view the week explains the shape. The vote is counted after tonight’s close, and the nine-day window is the shortest gauge that holds both the result and the data that follow. Beyond it the curve all but flattens: the three-month gauge sits only 2% above the VIX, the narrowest gap in our store.
In our view the reading that may cut the other way is the level. The VIX, the nine-day and three-month gauges, the volatility of the VIX and implied correlation, a gauge of how closely stocks are expected to move together, all closed at the highest in our store. That leans toward a broader repricing than one event, not only a bid for a few busy sessions.
The S&P 500 fell 0.51% to 7,541.40 and the Nasdaq 100 1.39%, more than 10% below its 7 October close, while the equal-weighted index rose 0.73%. The week has used 28% of its band to the downside. The energy sector fund’s volatility rank posted one of the largest rises after Brent’s slide, and Monday’s flow gave no readable direction outside chip names.
That is the whole brief in one read. The sections below hold the detail behind each paragraph, with the charts, the full set of readings and the sources, for when you want to go deeper on one part.
Headline driver
Americans vote in the midterm elections today. The first major states close their polls at 01:00 CET on Wednesday, after the US cash close, so tonight’s session settles before any result is known. The one-day volatility gauge covers only that session; the nine-day is the shortest that holds the count, the refunding and payrolls.
Monday’s selling stayed in technology. The Nasdaq 100 fell 1.39%, more than 10% below its 7 October close, as doubts about the returns on AI spending persisted, and Oracle lost 8.8% on plans to raise USD 20 billion. After hours Apple slipped 2.8% on rising memory costs despite strong iPhone sales. Brent fell 8% on progress in US-Iran talks. This morning the Reserve Bank of Australia raised its cash rate to 4.85% but softened its guidance.
Market snapshot
- US (Monday 2 November close): S&P 500 7,541.40, down 0.51%. Nasdaq 100 27,989.82, down 1.39%. Dow Jones Industrial Average 51,989.19, up 0.41%. The equal-weighted S&P 500 rose 0.73%. The technology sector fund fell 2.95% and energy 3.96%, while consumer discretionary rose 2.41% and financials 1.86%.
- Europe: the Stoxx 600 rose 0.42% to 649.45, the DAX 0.63% to 25,981.09 and the CAC 40 0.98% to 8,047.69, helped by lower oil. Euro-zone banks added 1.33%.
- Asia (Tuesday morning): the Kospi fell 3.35% to 5,662.90 by 06:00 CET as chip stocks slid, while the Hang Seng rose 0.52%.
- Commodities and rates: Brent trades at 104.81 and WTI at 96.64 after Monday’s slide. Gold futures sit at 3,936.50 and silver at 49.78. The two-year Treasury yield trades near 4.60% and the ten-year at 4.91%. High-yield spreads tightened one basis point to 339. Bitcoin trades near 76,600.
- Market regime: neutral / chop, the VIX at 21.15, the curve flat and SKEW elevated at 152.78.
Index levels and volatility readings from the watchlist export taken at 06:00 CET on 3 November 2026, which carries Monday’s US closes; oil moves, yield commentary and single-stock moves from the same-morning Saxo Market Quick Take. Past performance is not indicative of future results. Source: Saxo, Bloomberg, CBOE.
Volatility surface
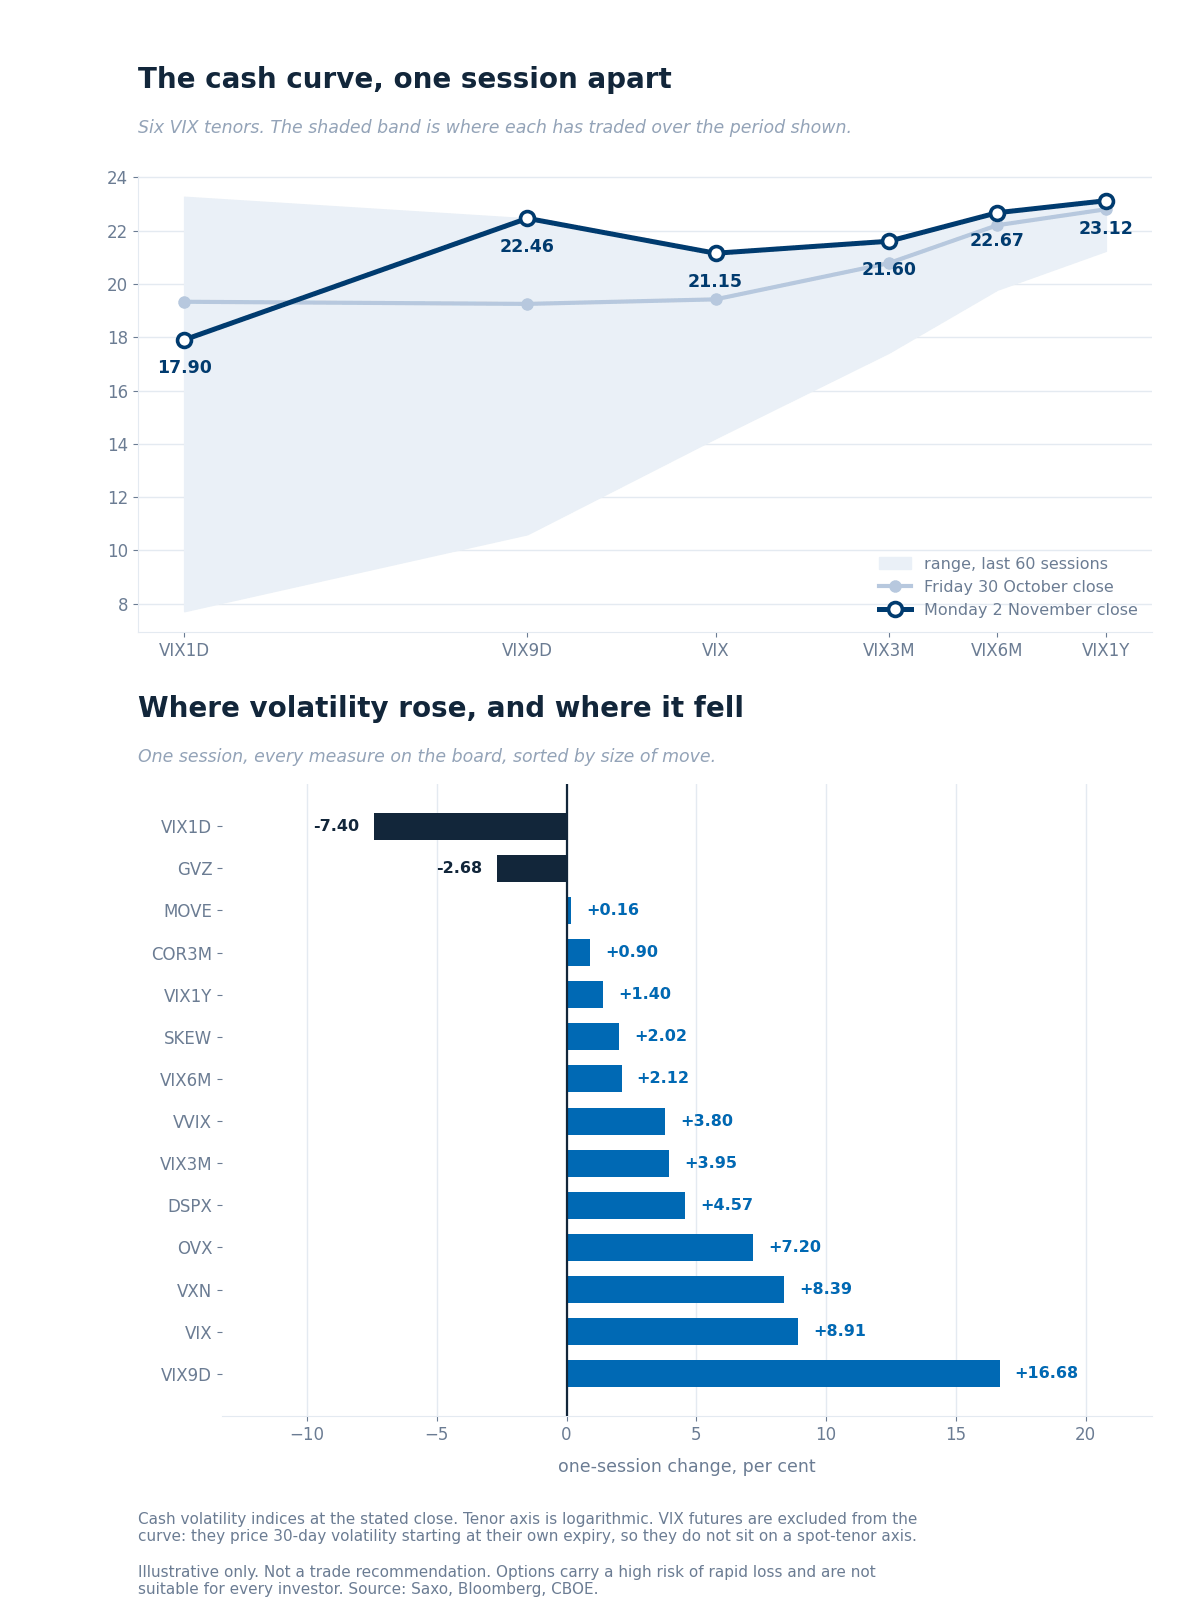
The cash curve at Monday’s close against Friday’s, over each tenor’s 60-session range, with the one-session change across every measure. Illustrative only. Past performance is not indicative of future results. Source: Saxo, Bloomberg, CBOE.
The curve grew a hump at nine days. The nine-day gauge rose 16.68% to 22.46 while the one-day fell 7.40% to 17.90. The VIX added 8.91% to 21.15 and the one-year only 1.40% to 23.12. VIX futures are left off the chart because each prices a month that starts at its own expiry.
Ratios. VIX9D/VIX rose to 1.062 from 0.99, only the fourth reading above one in our store and near its 1.085 high. VIX3M/VIX fell to 1.02 from 1.07, the lowest in our store, so the cash curve is in contango only narrowly. VXN/VIX holds at 1.46.
VIX futures. November reads 20.65 in overnight trade, below spot and above December at 20.01. Put-call parity on the 18 November options at Monday’s close returned 20.27, so the series has not rolled. November’s window starts on 18 November, after the vote.
Tails and correlation. SKEW rose 2.02% to 152.78, above its 145.95 median. Implied correlation edged up to 15.74, a new store high, and dispersion rose 4.57% to 39.14. The bond gauge barely moved at 100.37. The VIX, the nine-day and three-month gauges and the volatility of the VIX, at 110.47, also closed at the highest in our 101-session store.
Single-name volatility
The typical name repriced a little. On a common set of 523 underlyings the median implied-volatility rank rose to 42.9 from 40.6, and the mean to 46.6 from 44.2, with 373 names up and 136 down.
Energy moved most. The energy sector fund’s rank jumped 21.4 points to 93.9, among the largest rises in the universe, and the energy group’s median sits at 82.1, the highest of the ten groups we track. In our view that is the oil slide showing up in option prices, not the vote.
The Nasdaq 100 fund rose to 81.7 from 71.0 and the S&P 500 fund to 37.3 from 32.6, while the technology sector fund eased to 77.1 from 83.5. Apple went into its report at 84.3, the 98th percentile of its year, and AMD, which reports tonight, rose to 57.7 from 48.6.
Implied-volatility rank and percentile from the Saxo screener, read overnight to 03:24 CET on 3 November 2026, carrying Monday’s close. Source: Saxo.
Options flow sentiment
Based on end-of-day Monday 2 November, yesterday’s positioning, not today’s price action.
- Single-name flow leaned modestly bullish in chip names, where upside was bought after Friday’s fall. Elsewhere it carried no readable direction.
- Sector and ETF flow was hedging in shape at index level but mostly paired and long-dated. Eight of the ten categories showed no direction, so in our view the flow does not confirm a bid for the vote week.
Where the week's range sits
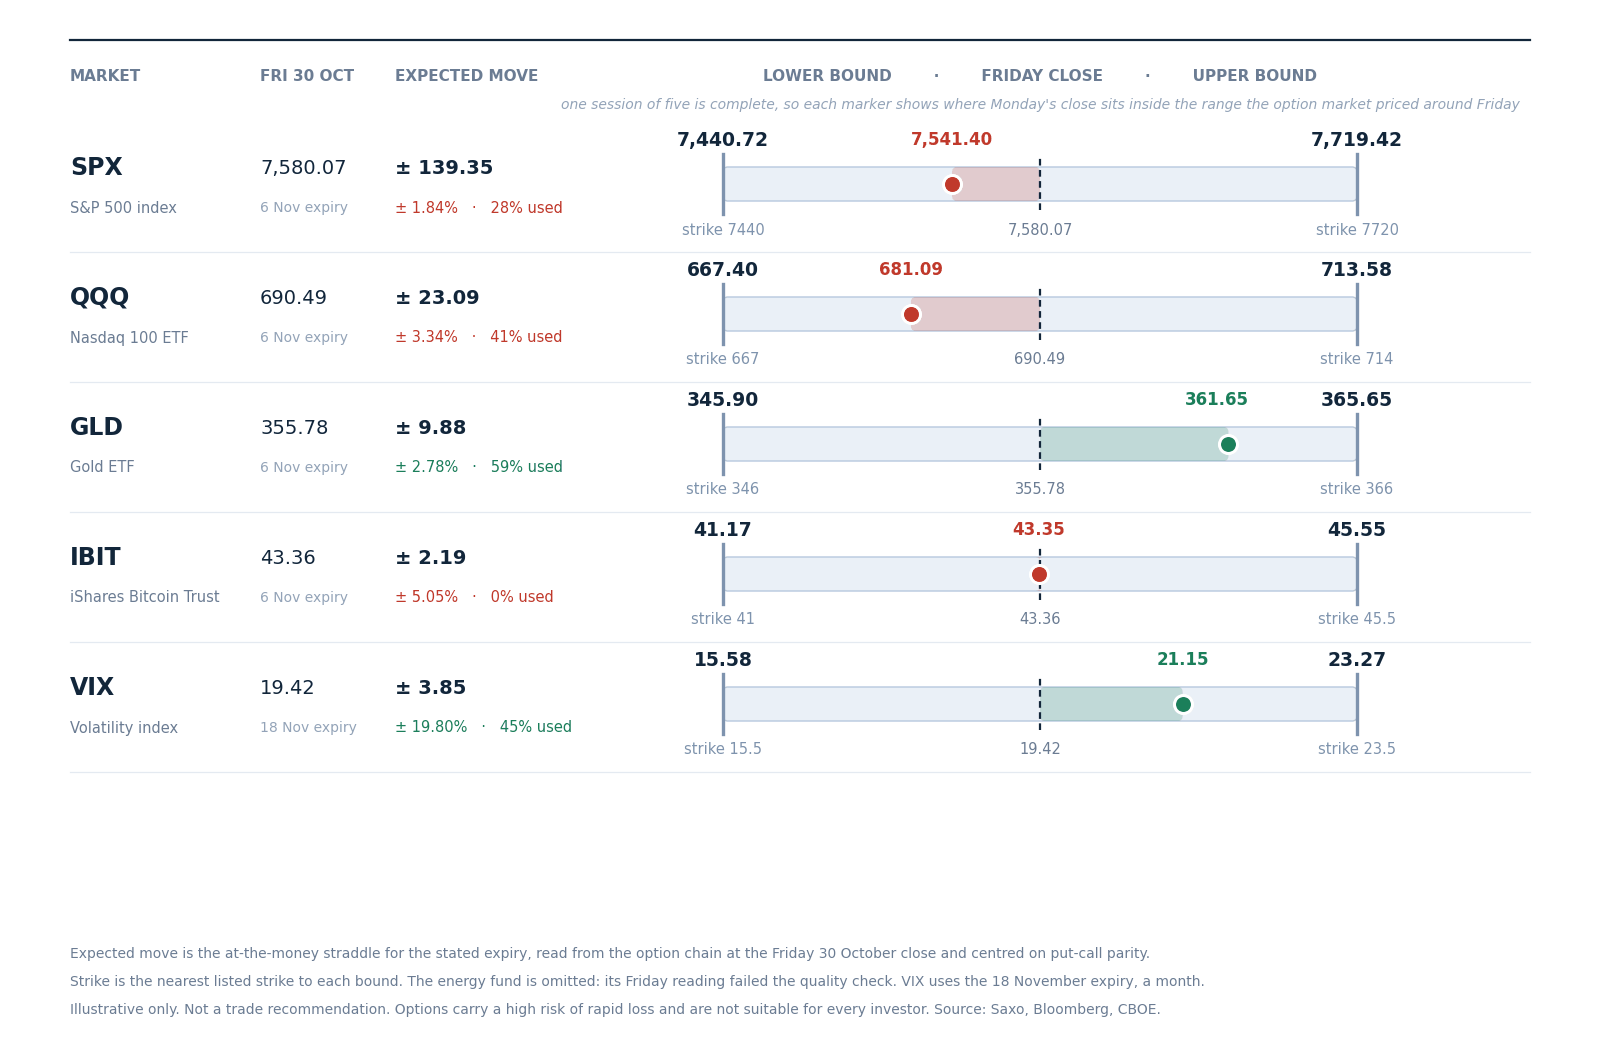
The range the option market priced for this week around Friday 30 October’s close, with each market’s Monday close marked inside it. Illustrative only, not a trade recommendation. Past performance is not indicative of future results. Source: Saxo, Bloomberg, CBOE.
The S&P 500 began the week with 139.35 points priced around Friday’s 7,580.07 close, 1.84%, from 7,440.72 to 7,719.42. Monday’s close at 7,541.40 has used 28% of that band to the downside, with four sessions left.
The Nasdaq 100 fund has used 41% of its band downward and gold 59% upward, while the bitcoin fund sits almost exactly on Friday’s close. The volatility row uses the 18 November expiry, so it measures a month, not a week, and has used 45% of its band upward. The energy fund’s Friday reading failed our quality check and is left out.
Options carry a high risk of rapid loss and are not suitable for every investor. Costs and charges apply and vary by account and venue; check the rates applicable to you.
Today's catalysts
- 16:00 CET US job openings and factory orders for September.
- US midterm elections: the first major states close their polls at 01:00 CET on Wednesday, with Pennsylvania, Michigan and Texas from 02:00 CET.
- Earnings today: AMD and Shopify, with Pfizer, Amgen, Arista Networks and Booking Holdings.
- This week: the Treasury’s quarterly refunding and Novo Nordisk on Wednesday; the Bank of England and Norges Bank on Thursday; payrolls on Friday.
Earnings scorecard
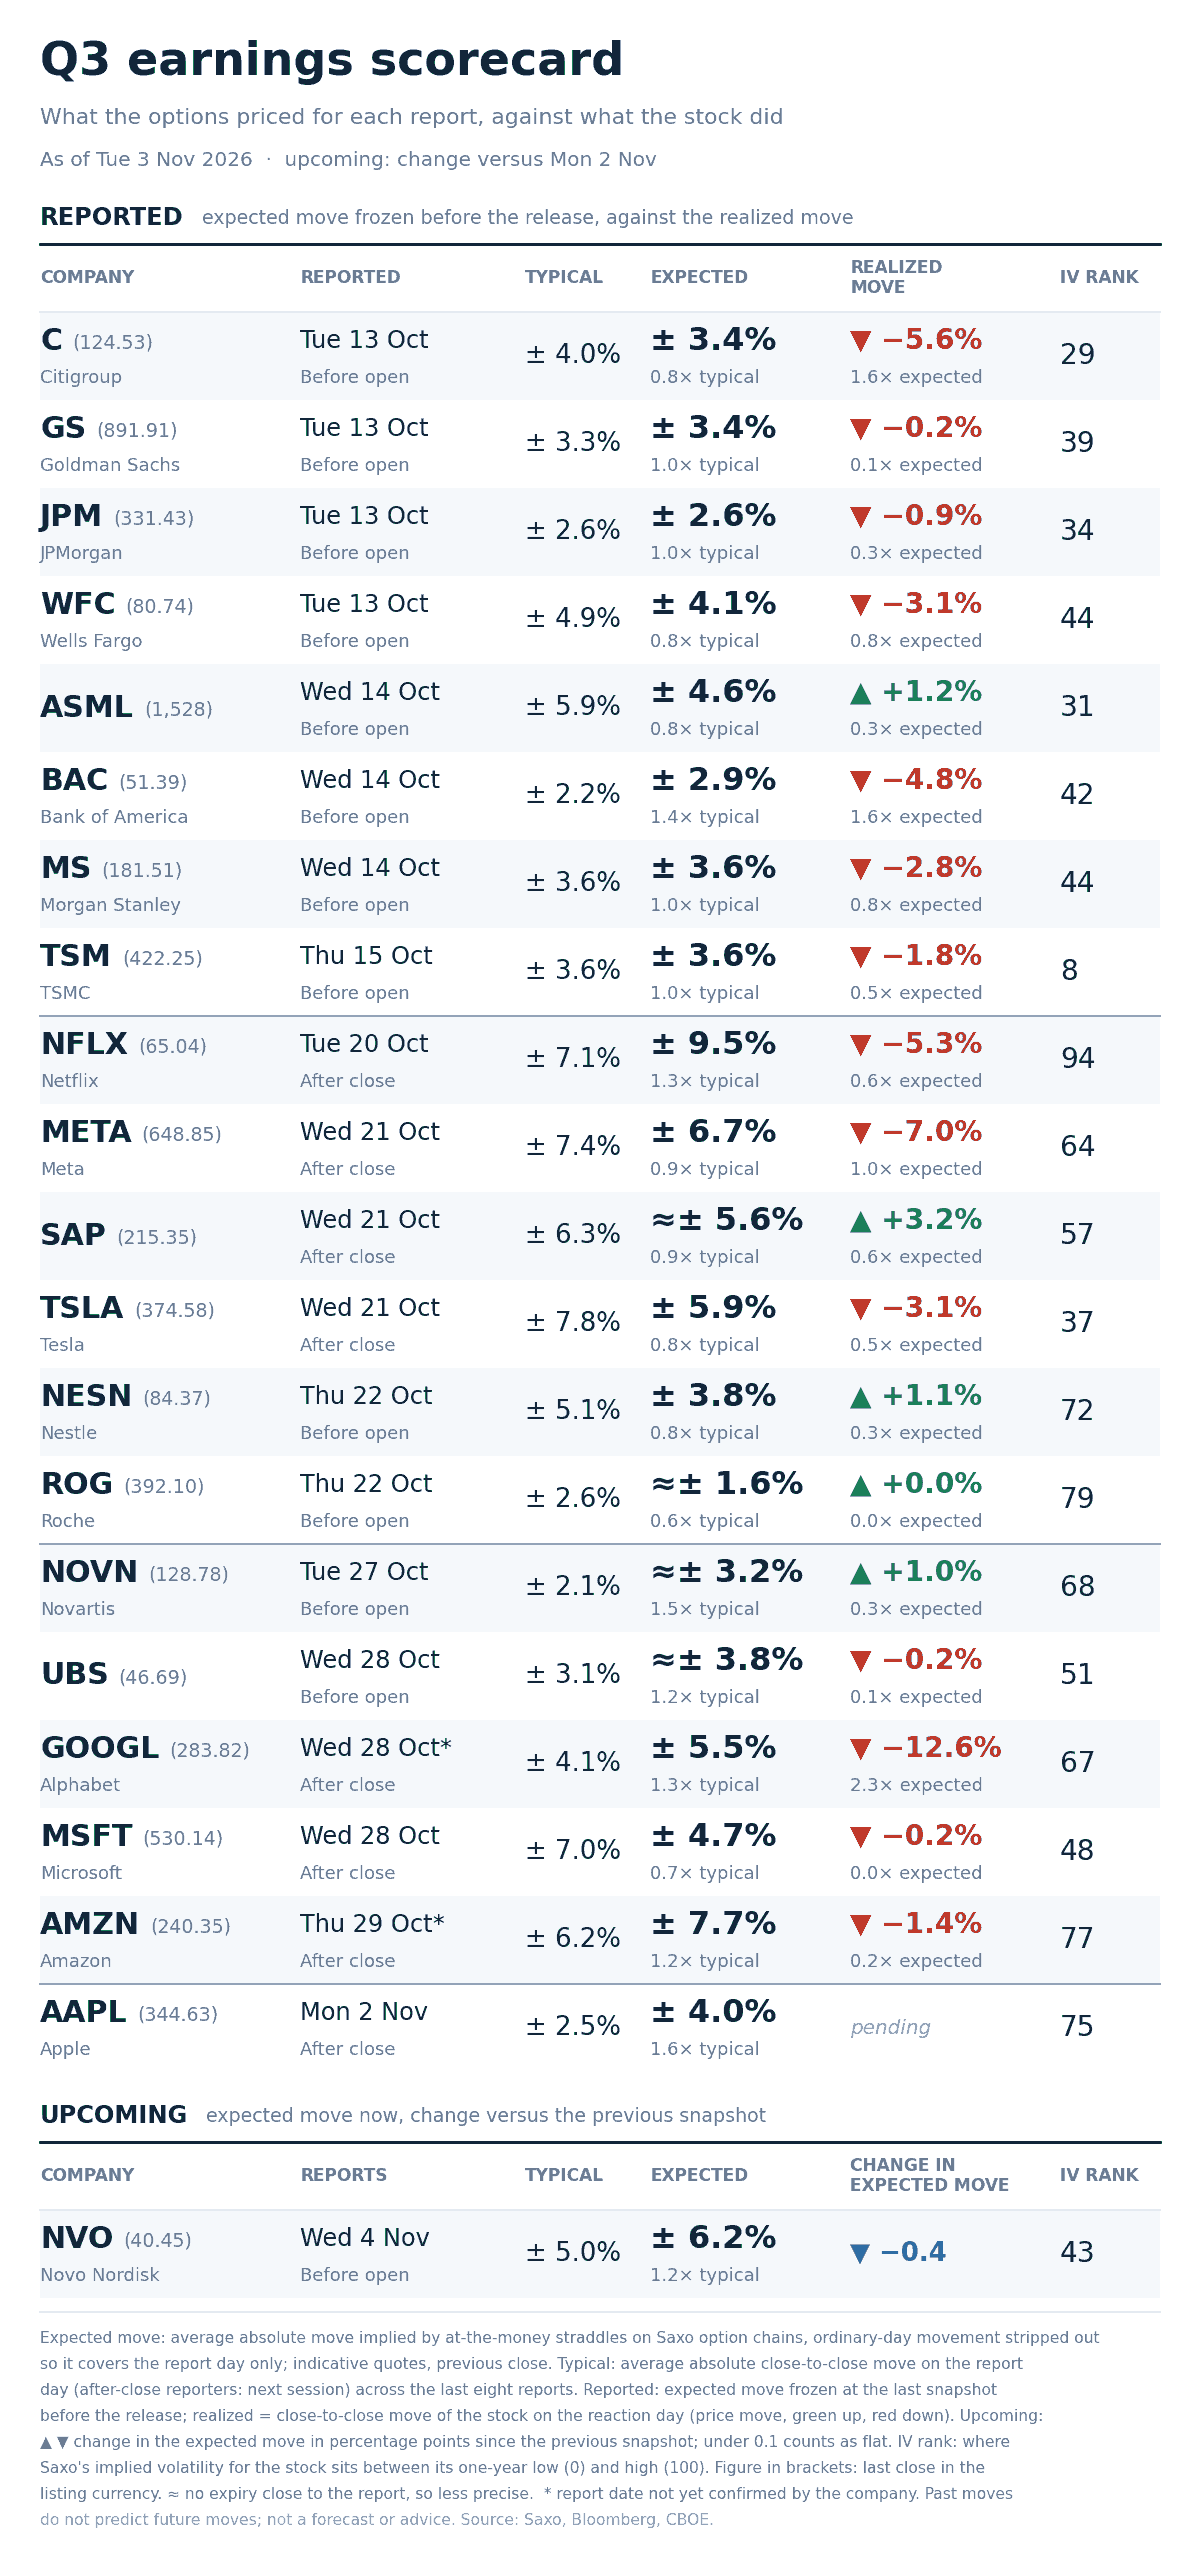
Option-implied expected move for each report day against the stock’s average move after its last eight reports, across the twenty-one names tracked this season. Past performance is not indicative of future results. Source: Saxo, Bloomberg, CBOE.
Apple reported last night priced for 4.0% against an eight-report average of 2.5%, the richest on our board. It slipped 2.8% after hours, so the realised move is still pending until today’s close.
Novo Nordisk, the last name on the board, reports on Wednesday priced for 6.2% against 5.0%, 1.2x its own history, down 0.4 points since yesterday, on a rank of 43.
Twenty of the twenty-one names have now reported. Alphabet’s 12.6% fall against 5.5% priced remains the largest miss of the season.
Options carry a high risk of rapid loss and are not suitable for every investor. Costs and charges apply and vary by account and venue; check the rates applicable to you.
What the market is pricing
- Session implied range: S&P 500 options price 64.70 points, 0.86%, for today’s expiry, which settles at the 22:00 CET close, before any result is known. Read before the US open, so indicative. The one-day gauge at 17.90 implies about 1.13%, a one-sigma figure rather than an expected move.
- Event repricing: yesterday the 6 November expiry priced 1.84% with five sessions to run. Time decay alone would have left about 1.65%. Today it prices 1.85%, so in our view the option market added premium to this week for a second day.
- Curve read: the nine-day gauge sits 6% above the VIX while the three-month sits only 2% above it. In our view that leans toward the market paying for the count and the data specifically, more than for a longer stretch of stress.
- Level read: the VIX, the volatility of the VIX and implied correlation all closed at the highest in our store. In our view that suggests the premium is not confined to the vote week, even if that is where it is steepest.
In our view this week tests whether the hump at nine days is an event premium that drains once the count and payrolls are out, or the front edge of a higher floor. Options carry a high risk of rapid loss and are not suitable for every investor. Costs and charges apply and vary by account and venue; check the rates applicable to you. Past performance is not indicative of future results.
| More from the author |
|---|