
Nvidia post-earnings

Nvidia earnings: Why isn’t the market cheering?
Key points:

  • Nvidia’s blockbuster results couldn’t clear sky-high expectations, triggering a sell-the-news reaction.
  • Slowing revenue growth and China export risks spotlight the potential for multiple compression in AI leaders, especially given crowded positioning.
  • Markets are now balancing the long-term AI narrative with a tilt toward defensives and broader diversification.


Why Nvidia underwhelmed

Nvidia’s latest results once again smashed through consensus numbers—revenue rose 56% YoY to $46.7B, and Q3 guidance of around $54B topped estimates. Yet markets sold off. Why?

  • The growth curve is flattening: The company’s extraordinary triple-digit growth from 2023–24 is decelerating. Investors now worry that slower revenue expansion means earnings multiples could compress, even if absolute profits remain stellar.
  • Data-center line underwhelmed: This segment has been the growth engine of Nvidia’s AI dominance. While still strong, results fell short of “whisper” expectations on Wall Street—enough to cool the AI frenzy.
  • Policy overhangs persist: Nvidia reported zero sales of its H20 AI chip to China during the quarter. With U.S.–China tech tensions simmering, export restrictions remain a key risk to future growth.
  • Crowded positioning: Nvidia had run up sharply into earnings, carrying outsized weight in indices. After the S&P 500 closed at a record, investors took the chance to lock in profits.

The result: a sell-the-news wobble rather than an AI funeral.
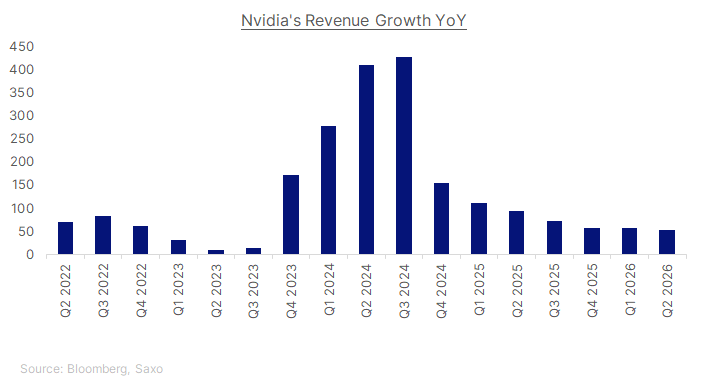
Nvidia revenue

How to position now

The bigger question for investors is not whether AI is over—it’s how to adjust exposures in this next phase.

Trim concentration risk

Nvidia remains a cornerstone of the AI trade, but extreme concentration in one name makes portfolios fragile.

  • Upstream: Diversify beyond Nvidia into broad semiconductor ETFs (SOXX, SMH).
  • Midstream: Add exposure to cloud and infrastructure names powering AI adoption (V9N – Data Centers & Digital Infrastructure UCITS).
  • Downstream: Robotics and automation ETFs (BOTZ) provide exposure to AI applications beyond chips.

Watch global chipmakers

  • Korea and Taiwan semis: Expect short-term drag as these names are most correlated with Nvidia’s cycle.
  • China chipmakers: Policy tailwinds could turn this dip into opportunity. Companies like Cambricon have just reported record profits on surging domestic demand, reinforcing Beijing’s drive to localize AI hardware.

Balance growth with defensives

  • With Fed rate cuts likely in sight, investors may want to balance AI exposure with income strategies (dividend stocks, REITs, investment-grade bonds).
  • Sectors like utilities, consumer staples, and healthcare can provide ballast if tech multiples compress.

Risks to watch

  • Fed policy: The next two weeks bring PCE inflation and jobs data—both crucial for shaping the “Fed pivot” narrative.
  • Geopolitics: Any escalation in U.S.–China semiconductor restrictions could cap AI valuations.
  • Peak cycle fears: If the market concludes Nvidia’s Q3 guidance signals peak demand, multiples could compress more broadly across AI leaders.

Bottom line

Nvidia’s results highlight an important turning point: AI remains a transformative theme, but the market is no longer in hyper-exuberant discovery mode. From here, the trade requires more selectivity, diversification, and tactical income strategies.

Investors should resist the urge to chase every dip blindly, but equally avoid calling the end of the AI cycle too early. The winners of AI 2.0 will still create significant long-term value—but the path will be choppier.


This material is marketing content and should not be regarded as investment advice. Trading financial instruments carries risks and historic performance is not a guarantee of future results.
The instrument(s) referenced in this content may be issued by a partner, from whom Saxo receives promotional fees, payment or retrocessions. While Saxo may receive compensation from these partnerships, all content is created with the aim of providing clients with valuable information and options..

Disclaimer

Confidentiality and Usage:
You may not reproduce, distribute, or transmit this material or any portion thereof without prior written permission from Saxo.

Nature of Information:
The information provided herein is based on current market conditions and analysts' opinions, which may reflect personal views of the author, and are subject to change without notice. This material does not include a record of any trading prices, or an offer of, or solicitation for, or endorsement to enter into any transaction in any investment product. Any forecast on the economy, markets and economic trends of the markets provided is not necessarily indicative of the future or likely performance of the investment product subject of this material.

Responsibility and Liability:
Saxo accepts no liability for any use that may be made of these comments or for any consequences that arise from such use. Saxo does not guarantee the accuracy or completeness of any information provided and assumes no liability for any errors, omissions, losses, or damages resulting from the use of this information.

The information provided in this material is solely for information only. It is intended for general circulation and does not take into account the specific investment objectives, financial situation or particular needs of any particular person. Accordingly, it should not be relied on or treated as a substitute for specific advice concerning specific situations of any person. Please seek advice from a financial adviser regarding the suitability of any investment product taking into account your specific investment objectives, financial situation or particular needs before you make a commitment to purchase an investment product. In the event that you choose not to seek advice from a financial adviser, you should consider whether any investment product mentioned in this publication is suitable for you.

Notwithstanding the above, insofar as any information provided herein contains research analyses or reports concerning any investment product authored by any foreign research house and is issued or promulgated to a person in Singapore who is not an accredited investor, expert investor, and/or institutional investor, Saxo Capital Market Pte. Ltd. accepts legal responsibility for the contents of this material to the extent required by law. Recipients of such material are to contact Saxo Capital Markets Pte. Ltd. in respect of any matters arising from, or in connection with, this material.

Risk Disclosure:
Trading in investment products involve significant risk, including the risk of losing your entire investment. Historical returns are not a guarantee of future returns. Prices can both rise and fall, and there is a risk that you will not get back the money you invested.

Conflicts of interest:
The author may hold positions in the investment products mentioned. The author does not own positions in the underlying investment product exceeding 0.5% of its market capitalisation, save as otherwise declared. The author is not permitted to trade the mentioned investment products within the first 24 hours after the publication of this article.

Saxo maintains partnerships with companies that compensate Saxo for promotional activities conducted on its platform. Additionally, Saxo has agreements with certain partners who provide retrocession contingent upon clients purchasing specific investment products offered by these partners. While Saxo receives compensation from these partnerships, all content is conducted with the intention of providing clients with valuable options and information.

Publication details:
If any listed companies are the subject of the material, the content has not been submitted to the companies in question prior to publication.

Please refer to our full disclaimer and notification on non-independent investment research for more details.

Saxo Markets
88 Market Street
CapitaSpring #31-01
Singapore 048948

Contact Saxo

Singapore
Singapore

Saxo Capital Markets Pte Ltd ('Saxo Markets') is a company authorised and regulated by the Monetary Authority of Singapore (MAS) [Co. Reg. No.: 200601141M ] and is a wholly owned subsidiary of Saxo Bank A/S, headquartered in Denmark. Please refer to our General Business Terms & Risk Warning to consider whether acquiring or continuing to hold financial products is suitable for you, prior to opening an account and investing in a financial product.

Saxo is part of the J. Safra Sarasin Group.

Trading in financial instruments carries various risks, and is not suitable for all investors. Please seek expert advice, and always ensure that you fully understand these risks before trading. Trading in leveraged products such as Margin FX products may result in your losses exceeding your initial deposits. Saxo Markets does not provide financial advice, any information available on this website is ‘general’ in nature and for informational purposes only. Saxo Markets does not take into account an individual’s needs, objectives or financial situation.

The Saxo trading platform has received numerous awards and recognition. For details of these awards and information on awards visit www.home.saxo/en-sg/about-us/awards.

The information or the products and services referred to on this website may be accessed worldwide, however is only intended for distribution to and use by recipients located in countries where such use does not constitute a violation of applicable legislation or regulations. Products and Services offered on this website are not intended for residents of the United States, Malaysia and Japan. Please click here to view our full disclaimer.

This advertisement has not been reviewed by the Monetary Authority of Singapore.

Apple and the Apple logo are trademarks of Apple Inc, registered in the US and other countries and regions. App Store is a service mark of Apple Inc. Google Play and the Google Play logo are trademarks of Google LLC.