
Access all our platforms from a single account.

How to trade an earnings event with options: a Netflix case study

Summary: Netflix reports on 16 July after the close, and the options market is pricing a roughly 8% move by Friday. Using that number as the anchor, this article walks through how to trade an earnings event with options, mapping a bullish call diagonal, a neutral iron condor and a bearish put broken-wing butterfly to the expected-move range - with Netflix as the worked example.
Earnings are a scheduled uncertainty – the date is known, the outcome is not. The craft lies in pricing the move and choosing a structure that fits the trader’s view; the actual number is almost beside the point.
Every quarter a company reports and its stock gaps. For an options trader, the interesting part is not guessing the result – the market has already priced how far the stock might move, and that price sits in the options chain before the event. Trading earnings well starts with reading that price, not with a fundamental forecast.
This piece uses Netflix (NFLX) – reporting after the US market close on 16 July 2026 (Source: Netflix Investor Relations, as of 15 June 2026) – as the example. The stock last traded near $73.83 (Source: Saxo, as of 13 July 2026 close), and, as is typical into a report, its near-dated implied volatility is elevated. For traders considering the event, the question is whether the risk/reward justifies a position – and, if so, how to structure it with defined risk rather than an outright bet into a binary catalyst.
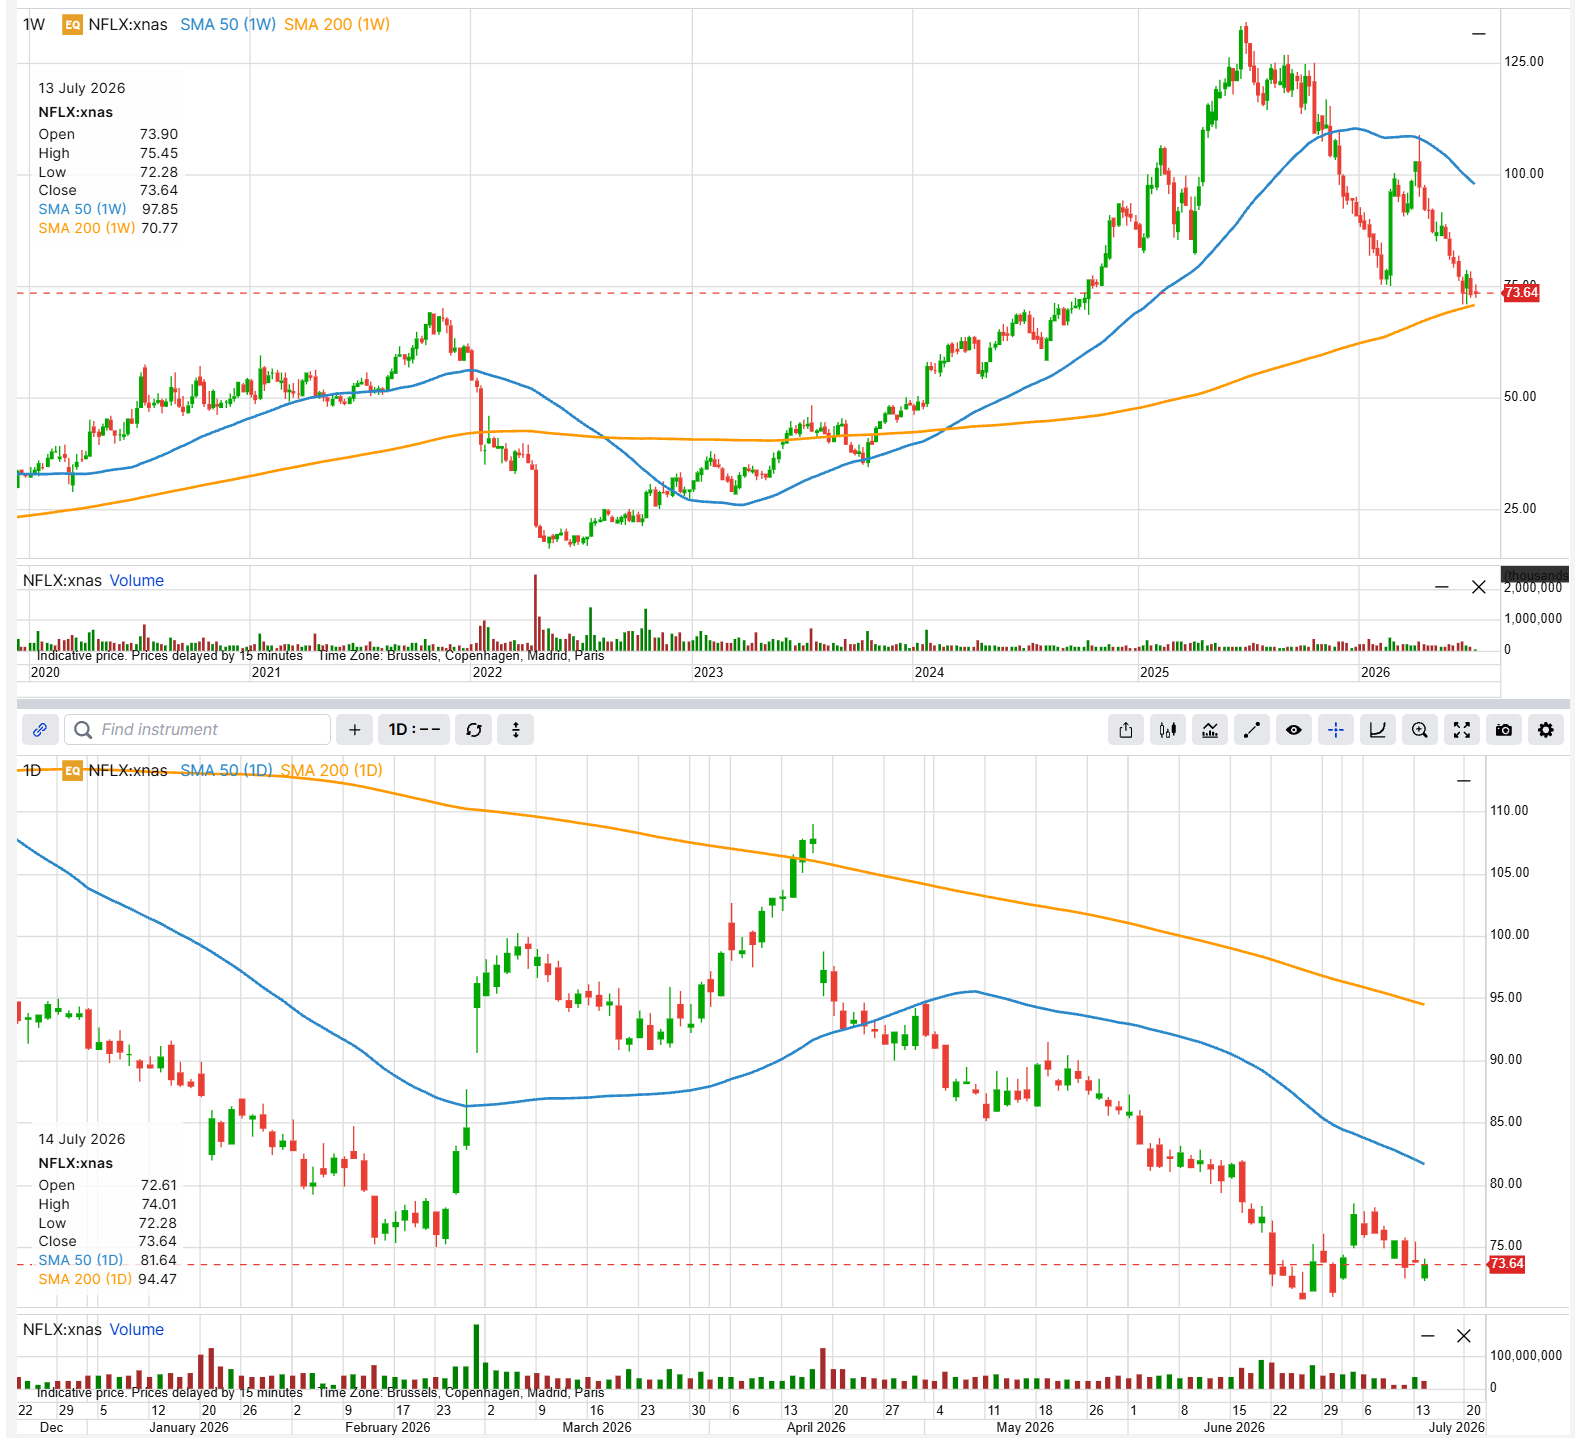 NFLX heads into earnings testing long-term support – the 200-week moving average near $71 – after sliding from above $100 earlier in the year. Illustrative and educational, not predictive. Source: SaxoTrader, as of 14 July 2026
Past performance is not indicative of future results. This chart is illustrative and for educational purposes only; it is not predictive.
Step one: read the expected move
A common way to estimate the market-implied move is to add the at-the-money call premium and the at-the-money put premium for the expiry that captures the event. That combined straddle price is a rough proxy for how much movement option buyers are paying for.
For Netflix, the July 17 weekly is the expiry that matters, because the company reports the evening before it expires. At the $74 strike the call was near $2.93 and the put near $3.05 – a straddle of about $5.98 (Source: Saxo option chain, indicative pre-open as of 14 July 2026). Against ~$73.83, that is roughly an 8% expected move, an implied range of about $68 to $80 – the yardstick every structure below is measured against.
Step two: respect the volatility crush
Earnings options are expensive because of implied volatility. Into the event, implied volatility in the nearest expiry is bid up; once the result is out, it collapses regardless of direction – the “IV crush.” A trader can be right on direction and still lose on a long option if the crush outweighs the move.
Netflix shows the textbook shape: July 17 at-the-money implied volatility above 100%, August near 47%, September near 42% (Source: Saxo, as of 14 July 2026). In our view a term structure that front-loaded argues against buying naked front-week premium and gives net-selling structures a tailwind – though a large enough move can still overwhelm any crush, which is why each example below is defined-risk.
Important note: The strategies and examples provided in this article are purely for educational purposes. They are intended to assist in shaping your thought process and should not be replicated or implemented without careful consideration. Every investor or trader must conduct their own due diligence and take into account their unique financial situation, risk tolerance, and investment objectives before making any decisions. Remember, investing in the stock market carries risk, and it’s crucial to make informed decisions.
Bullish view: upside without overpaying for volatility
For a bullish view into earnings that is reluctant to pay peak volatility for a call, a long call diagonal is one educational example: a longer-dated call for the directional exposure, financed in part by a shorter-dated, higher-strike short call that sells the most inflated premium.
The following examples are hypothetical and for educational use only; they are not advice or trade recommendations. On Netflix, with the $80 area holding the heaviest call open interest as a near-term ceiling:
Example structure (illustrative only – not a trade recommendation)
- Buy 1 21 August 2026 $74 call
- Sell 1 17 July 2026 $78 call
- Net debit: approximately $3.12 ($312 per spread)
- Maximum risk (model-dependent): approximately the net debit if NFLX falls sharply
- Maximum profit (model-dependent): approximately $335 near $78 at the 17 July expiry
- Break-even at the 17 July expiry: approximately $72.30
Risk: the maximum loss is the net debit paid; profit and break-even are model-dependent, and a broad fall in implied volatility can hurt the long August leg. The short call carries early-assignment risk. Costs and charges apply to each leg; see Saxo pricing for full details.
The long August call provides upside exposure and outlives the event; the short July $78 call cuts the cost by selling the most inflated premium on the board – implied volatility above 100%, three days of life left. If Netflix does not blow straight through $78, that short leg is designed to decay quickly as post-earnings volatility falls. The position is profitable if NFLX holds above roughly $72.30 (about 2% below spot) at the 17 July expiry.
Strategy insight – vega cuts both ways. The position is net long volatility through the August call, so it may benefit if the front-week premium crushes while the August leg holds value; the risk is that a broad, lasting drop in implied volatility offsets that decay, and a gap far above $78 caps the near-term gain. Because those outcomes depend on the residual August call’s price, treat maximum profit and break-even as estimates, not fixed levels.
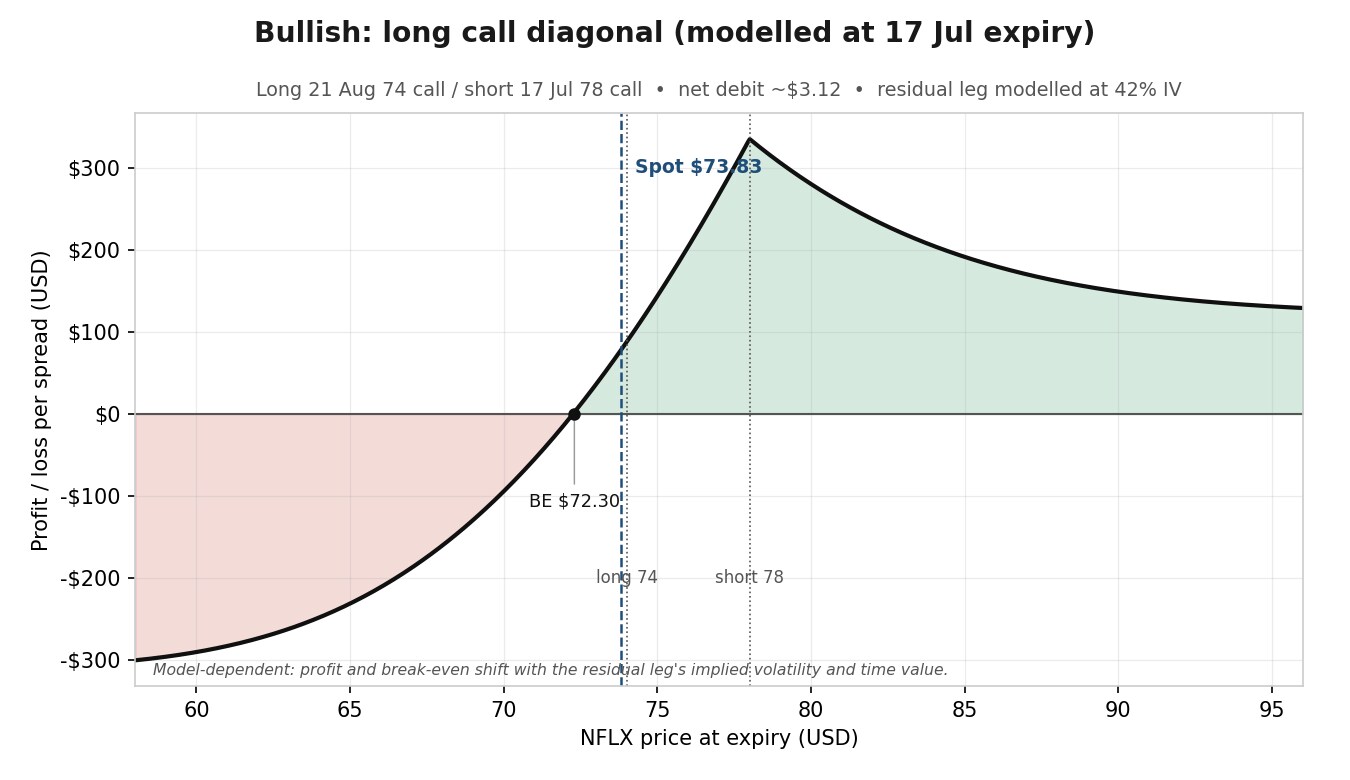 Long call diagonal, modelled at the 17 July expiry with the August leg at 42% implied volatility. Illustrative and educational only – not a trade recommendation, and not predictive. Source: SaxoTrader
Neutral view: selling the expected move
For a view that the market is over-pricing the move, a short iron condor is one educational example: it collects premium and may reach its maximum profit if the stock stays inside a chosen range, in effect selling the implied move in the hope the realised move is smaller.
On Netflix, the range is drawn in advance by the expected move and by open interest at the $70 and $80 strikes:
Example structure (illustrative only – not a trade recommendation)
- Sell 1 17 July 2026 $70 put, buy 1 17 July 2026 $65 put
- Sell 1 17 July 2026 $80 call, buy 1 17 July 2026 $85 call
- Net credit: approximately $1.61 ($161 per condor)
- Maximum risk: approximately $339 (the $5 wing width minus the net credit)
- Maximum profit: approximately $161, if NFLX finishes between $70 and $80
- Break-evens at expiry: approximately $68.45 and $81.61
Risk: the maximum loss is the wing width minus the net credit – about $339 – if NFLX settles beyond either long strike; short legs carry early-assignment risk. Costs and charges apply to each leg; see Saxo pricing for full details.
The two short strikes define the range the trader wants the stock to hold – here on the heaviest open interest in the 17 July chain, the $70 put and $80 call, levels that can act as support and resistance. The two long strikes cap the loss if the range breaks. The trade may benefit from the post-earnings crush, which speeds the decay of both spreads; the risk is defined – a move beyond either break-even turns the credit into a loss, up to the $339 maximum. With break-evens at $68.45 and $81.61, just outside the implied move, it is a bet that Netflix moves less than the market is pricing.
Strategy insight – selling the expected move. An iron condor into earnings is a short-volatility position: it may profit if the realised move is smaller than the implied one and loses if it is larger. Anchoring the shorts to the largest open-interest walls ties the range to where the market is positioned.
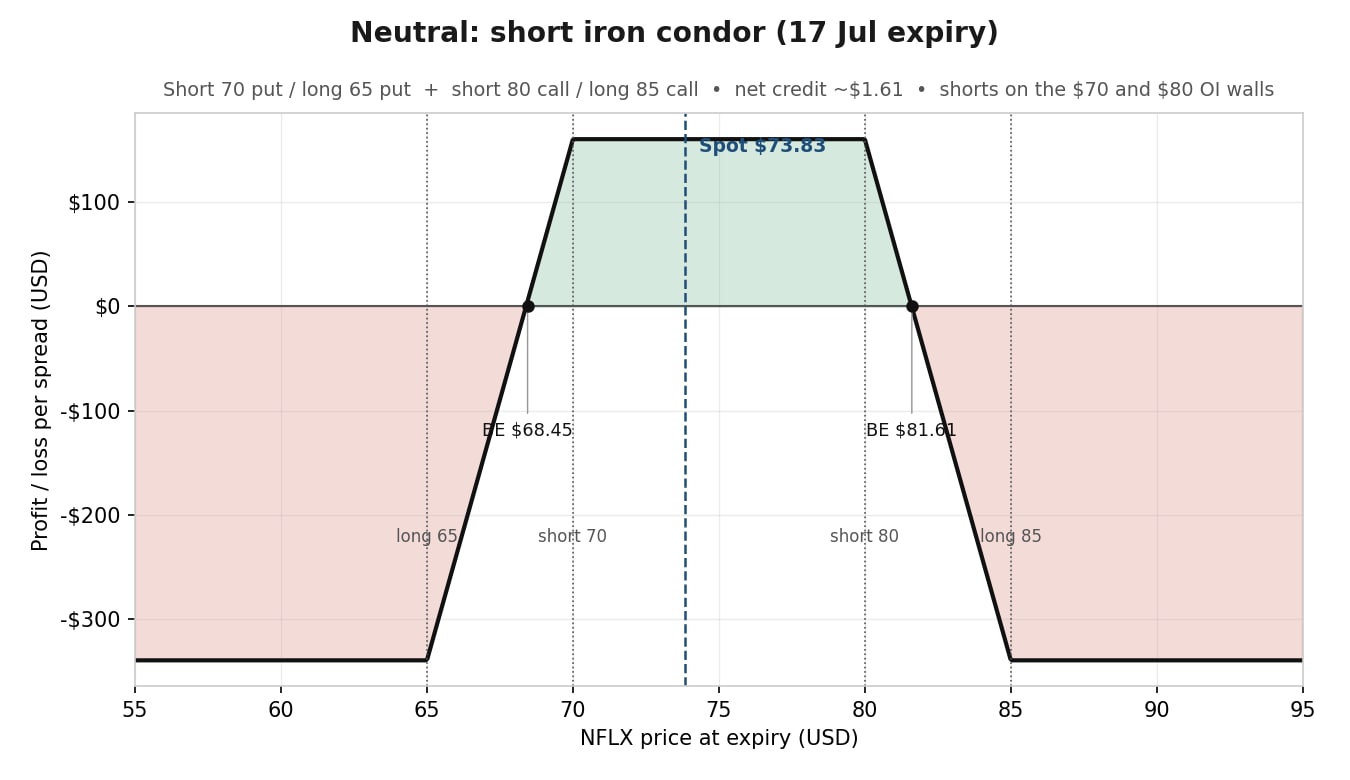 Short iron condor with shorts on the $70 and $80 open-interest walls. Illustrative and educational only – not a trade recommendation, and not predictive. Source: SaxoTrader
Bearish lean: targeting a level, cheaply
For a directional-down view that prefers not to buy a naked put at peak volatility, a put broken-wing butterfly is one educational example: it targets a specific downside zone for a small cost, with the wings deliberately skewed to reduce the risk on one side.
On Netflix, the $70 support level – the heaviest put open interest – is the natural target:
Example structure (illustrative only – not a trade recommendation)
- Buy 1 17 July 2026 $74 put
- Sell 2 17 July 2026 $70 puts
- Buy 1 17 July 2026 $64 put
- Net debit: approximately $0.74 ($74 per butterfly)
- Maximum risk: approximately $74 if NFLX rises, or approximately $274 if NFLX falls below $64
- Maximum profit: approximately $326 if NFLX finishes near $70
- Break-evens at expiry: approximately $66.74 and $73.30
Risk: the maximum loss is about $274 if NFLX falls below $64 (or the $74 net debit if it rises); the short puts carry early-assignment risk. Costs and charges apply to each leg; see Saxo pricing for full details.
The “broken wing” is the unequal strike spacing: $4 on the upper side ($74 to $70) versus $6 on the lower ($70 to $64). That asymmetry cheapens the structure and trims the upside risk to just the $0.74 debit – a rally through $74 expires for that small loss. The trade-off is on the downside: profit peaks if the stock drifts to $70, but a break below $64 gives a defined loss of about $274. It is a low-cost way to lean moderately lower, not a bet on a crash.
Strategy insight – the broken wing buys asymmetry. Skewing one wing nearly eliminates the risk on one side and finances the position, in exchange for a larger – but still capped – loss on the other. Here a quiet drift up costs almost nothing; the price is a fatter loss only if Netflix falls hard through the lower strike.
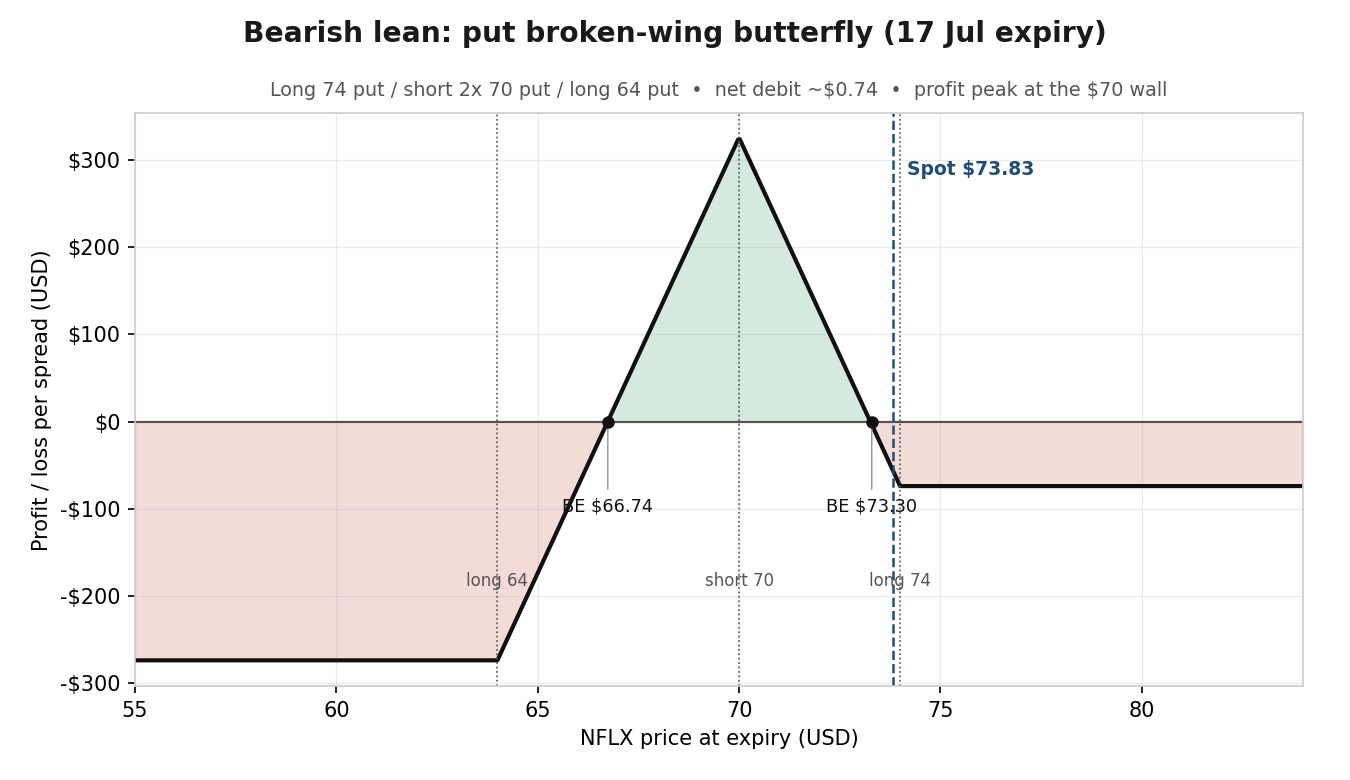 Put broken-wing butterfly targeting the $70 support wall. Illustrative and educational only – not a trade recommendation, and not predictive. Source: SaxoTrader
The expected move comes from the July 17 weekly because it captures earnings most directly. The diagonal’s long leg uses 21 August to give the recovery thesis more time; price that leg from the August chain, not by assuming the 8% front-week move applies to it unchanged.
Before placing an earnings trade, check:
- Bid/ask spreads – wide spreads can eliminate the theoretical edge at entry, especially in weekly wings
- Volume and open interest at the selected strikes
- Whether earnings are before the open or after the close – it determines which expiry captures the move
- Implied volatility relative to how much the stock typically moves on earnings
- An exit plan defined before entry, particularly for multi-leg structures
- Assignment risk on any short leg that moves in the money (see note below)
Assignment risk note: Because NFLX options are American-style, any short leg – the diagonal’s short call, the condor’s short strikes, the butterfly’s short puts – can be assigned before expiry if it moves in the money, particularly near expiration. Traders should monitor short options and understand the platform’s assignment process before entering.
See Saxo pricing for costs and applicable charges: Saxo pricing
Final thoughts
The method matters more than the ticker. Reading the expected move, anticipating the volatility crush, then matching a defined-risk structure to a view is a process that transfers to any earnings event; Netflix supplied the live numbers. Notice that none of the three structures needed a forecast of the actual result. Each started from what the market was already charging for the move and asked a different question: too cheap to sell, about right, or worth a cheap directional lean?
That reframing – from predicting the news to pricing the reaction – is the core of trading earnings with options. Whether the realised move lands inside or outside the implied range is unknowable in advance, which is why defined-risk structures, with the maximum loss known at entry, can be a more disciplined way to engage. Options carry a high risk of rapid loss and are not suitable for every investor. The expected move shows what the crowd is paying for the reaction; the trader’s job is to decide whether that price is worth taking, and on which side.
The author does not hold positions in any of the instruments mentioned in this article.
Sources: Netflix Q2 2026 earnings date – Netflix Investor Relations (ir.netflix.net); price, option premiums, implied volatility and open interest – Saxo platform, as of 13–14 July 2026.
This content is marketing material and should not be regarded as investment advice. Trading financial instruments carries risks and historic performance is not a guarantee of future results.
The Author is permitted to wait at least 24 hours from the time of the publication before they trade the instruments themselves.
The instrument(s) referenced in this content may be issued by a partner, from whom Saxo receives promotional fees, payment or retrocessions. While Saxo may receive compensation from these partnerships, all content is created with the aim of providing clients with valuable information and options.
This content will not be changed or subject to review after publication.
| More from the author |
|---|